My Investments Turned Negative, but I Couldn't Sell: Rereading Hayek's The Road to Serfdom
My investments turned negative and I struggled to sell. An AI agent developer trained in computer science and finance revisits Hayek on planning, freedom and fallible judgment.
On this page
The central question: Friedrich Hayek’s The Road to Serfdom is not best understood as a proof that every government intervention ends in dictatorship. Its strongest enduring challenge concerns what happens when comprehensive economic planning gives a central authority the power to rank competing social objectives, allocate resources and enforce those choices. The institutional concern is serious; the scope and inevitability of the resulting political danger remain disputed.
Why this book resonates with my work and investing
I grew up in a remote mountain area. I studied computer science as an undergraduate, then switched disciplines to study finance in graduate school. Today I work in software, including AI-agent development, build independent software projects, and invest on the side. These paths have taught me to care about incomplete information, institutional constraints and how decisions can be corrected.
Recently my own investing has been painful. My year-to-date performance turned negative on Wednesday, October 14, 2026, and the loss has widened today. I have found it hard to sell at a loss. I am describing my experience, not presenting verified brokerage returns, position details or an investment recommendation. Studying finance has not made me immune to attachment to an investment thesis; working with complex software does not make its outcomes fully controllable either.
In agent engineering, I think about permissions, tool failures, audit trails and the need for human intervention. Investing also calls for acknowledging incomplete information and creating a process for updating decisions. Yet Hayek’s book is about comprehensive economic planning and political power—not a technical guide to cutting individual trading losses. The parallel here is a personal prompt to examine my own certainty, not a claim that the two problems share the same mechanism.
Testing the reading question against a real loss
The question I bring to this reading is whether I can revise a confident judgment when reality stops supporting it. This is my own question prompted by a discussion of institutions and correction, not an investment rule derived from Hayek.
What has reality actually established? Under my account’s year-to-date calculation, performance turned negative on October 14, 2026, and the losses widened on October 19. I have been reluctant to close my positions. These facts show both pressure on my original thesis and an emotional reluctance to sell; they do not establish that selling immediately would have been correct. Without verified trade records, position weights and a written investment thesis from the time, I cannot honestly claim a rigorous return attribution or backtest.
For the next review, I intend to record the original rationale for each significant holding, conditions that would disprove it, its risk limits and new evidence as separate items. I can then revisit the decision rather than treating the current unrealized loss as the only signal. This is a proposed practice, not a process that I have already validated as effective.
Why the year 1944 matters
The title often serves as a shortcut in contemporary arguments about markets and government. That loses the circumstances in which the book appeared. It was first published in Britain in 1944 and reached American readers through the University of Chicago Press that September.
Bruce Caldwell’s history of the book traces its origins to Hayek’s arguments about socialist economic calculation and planning in the 1930s. Wartime mobilization had demonstrated the state’s capacity to coordinate production, and some prominent voices wanted planning to guide postwar reconstruction as well. The question was not simply whether government should provide a service. It was whether wartime forms of coordination should become the organizing principle of peacetime economic life.
The definitive edition’s table of contents is revealing: “Planning and Democracy,” “Planning and the Rule of Law,” “Economic Control and Totalitarianism,” and “Security and Freedom” put institutional questions alongside economic ones. The analysis below is grounded in verified bibliographic and historical scholarship; it is not presented as a page-by-page close reading of an unavailable edition.
Why planning is not merely a technical optimization problem
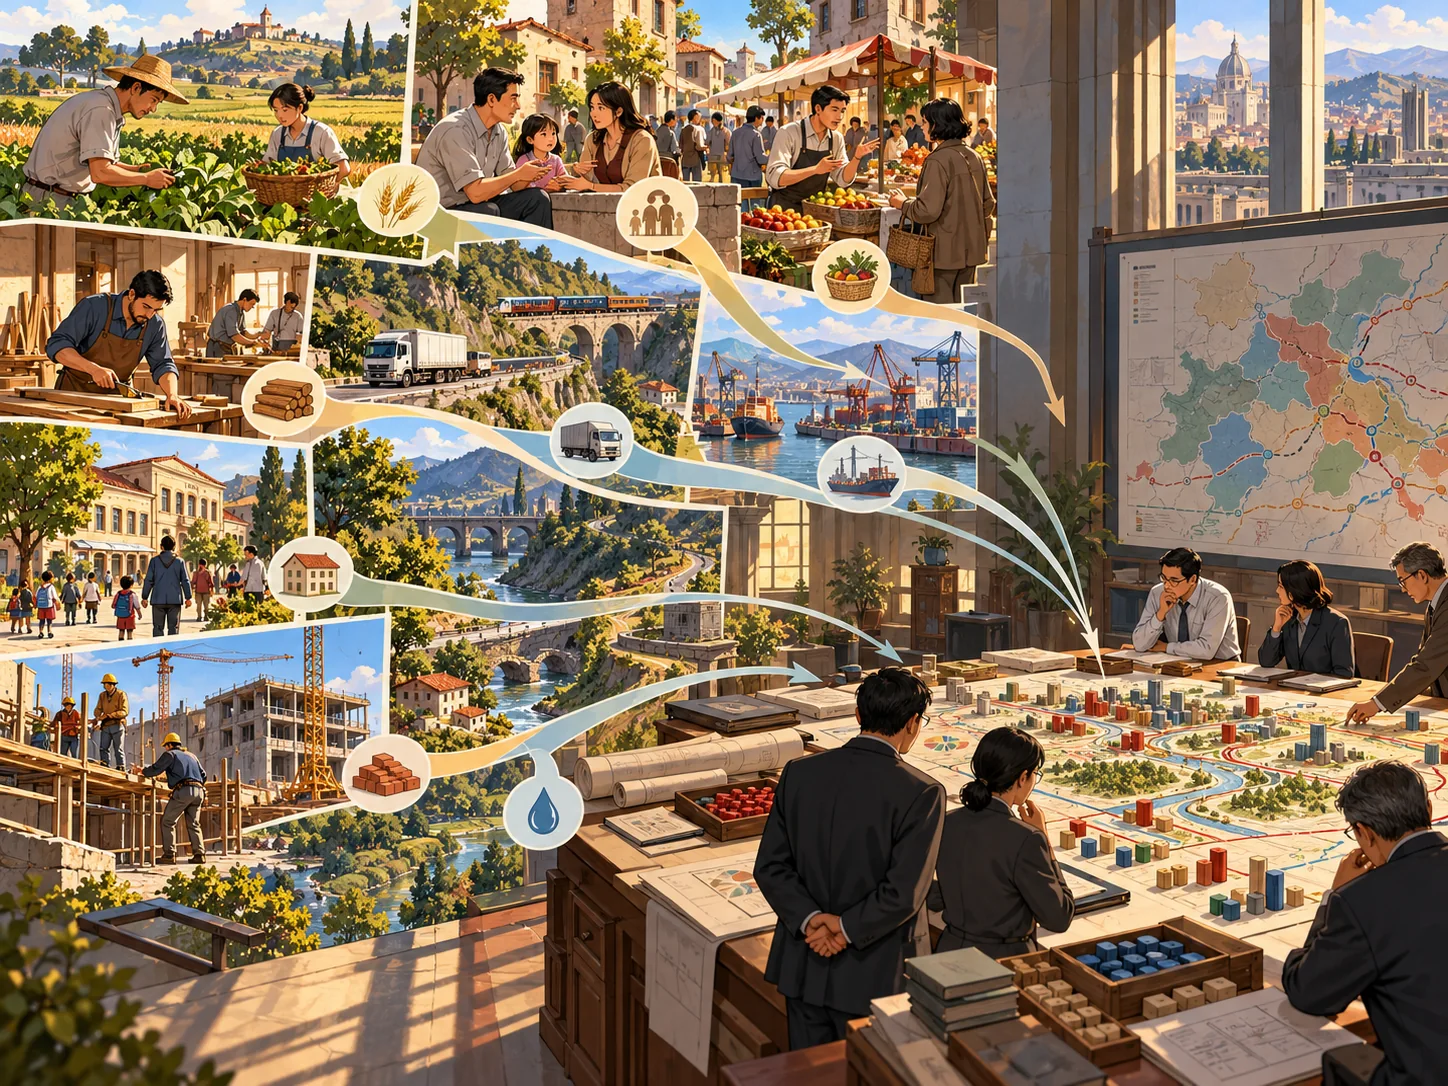
Households, firms and governments all plan. A factory schedules production; a city coordinates roads; a family budgets for the future. Hayek’s more demanding target is comprehensive planning in which a central institution acquires binding authority over the economy’s allocation decisions.
Imagine that one authority must assign scarce energy, housing, materials and labor across hospitals, factories, residential development and defense. Better forecasting may improve its calculations, but cannot tell us whose goals should prevail when reasonable people disagree. The choices imply judgments about deservingness, urgency, fairness and sacrifice.
In a decentralized order, individuals pursue different ends, revise them and respond to changing prices and constraints. This is not a guarantee of perfect outcomes, nor does it eliminate power imbalances. Yet a plurality of decision-makers does not require everyone to assent to one official ranking of desirable lives.
Hayek’s worry was that a comprehensive allocation system turns disagreements over resources into contests over political command. The planners who determine priorities may also need the power to enforce them. If there are inadequate limits on that authority, the ability to dissent and correct mistakes may diminish.
This is a proposed institutional mechanism, not a verified numerical law connecting the government-spending share of GDP to totalitarianism.
The rule-of-law question
The chapter topic “Planning and the Rule of Law” is useful precisely because it shifts attention away from a simplistic intervention-versus-no-intervention argument.
General, known and reviewable rules allow people to organize their affairs without asking for discretionary permission at every turn. A selective order aimed at a named firm or individual is different from a general environmental or competition rule applied impartially. Both are state actions; their implications for predictability and freedom can diverge.
That distinction does not mean that every rule is beneficial or that public provision is always efficient. Pollution, market dominance, asymmetric information and public infrastructure pose real coordination problems. The better test concerns design and accountability: Who decides? Under what authority? Are similarly situated participants treated alike? What evidence could lead to revision?
Where the slippery-slope claim faces genuine objections
The most disputed part of the argument is the strength of the causal link from economic planning to political repression.
Read expansively as the assertion that any move toward a mixed economy must end in dictatorship, the argument encounters obvious historical challenges. Alves and Meadowcroft emphasize the observed stability of mixed economies and question an inexorable slippery slope. Other scholarship asks whether that broad interpretation accurately captures the kind of comprehensive planning Hayek was addressing.
A 2025 study in History of Political Economy reconstructs contemporary definitions of socialism, planning and welfare from 1930 to 1950, arguing for a narrower understanding centered on state control of production. Trantidis and Cowen offer a related but distinct institutional reading: risks may arise from discriminatory coercion and command-and-control interventions rather than from public spending as a single aggregate measure.
These contributions do not settle the disagreement. They do, however, improve the questions worth asking: Are decisions contestable? Are rules general or selective? Can a government change course without punishing dissent? Do institutions constrain those allocating resources?
Hayek should neither be reduced to a slogan against every public service nor insulated from historical counterexamples.
What investors and business operators can usefully take from it
This is political economy, not a stock-picking formula. The investor’s legitimate takeaway is to make institutional assumptions explicit rather than treating the regulatory environment as an immutable backdrop.
For a capital-intensive company, useful questions include:
- How long must its investment remain productive before it earns an adequate return?
- Does entry depend on transparent rules or discretionary permissions?
- How reliant is the business model on a single subsidy, license or administrative relationship?
- Can management adapt output, prices and costs as conditions change?
- Do operating cash flows support the strategy, or are nonrecurring investment gains being mistaken for recurring profitability?
A public investment program may solve a genuine infrastructure bottleneck; an impartial standard may promote competition; a targeted privilege may entrench incumbents. No single label—“market” or “state”—replaces an examination of mechanisms, evidence and counterexamples.
What not to conclude
Do not equate Hayek’s arguments with the abolition of government. Do not project every feature of a 1944 wartime dispute onto contemporary welfare arrangements. Do not use historical analogies as substitutes for causal evidence. And do not presume that the survival of some mixed-economy democracies proves institutional risks from unconstrained authority can never emerge.
The durable insight worth testing is narrower and more productive: an economic arrangement must be evaluated not only for efficiency, but also for how it distributes decision-making power, limits coercion and makes correction possible.
Related reading: antifragility and optionality, mental models, and independent developer cash runway. These are separate reflections on uncertainty, not trading rules supplied by Hayek.
Sources and verification limits
- University of Chicago Press, The Road to Serfdom: Text and Documents—The Definitive Edition: https://press.uchicago.edu/ucp/books/book/chicago/R/bo4138549.html
- Bruce Caldwell, “The Publication History of The Road to Serfdom”: https://press.uchicago.edu/Misc/Chicago/320553.html
- Bruce Caldwell, “The Road to Serfdom after 75 Years,” Journal of Economic Literature (2020): https://www.aeaweb.org/articles?id=10.1257/jel.20191542
- “The Road to Serfdom and the Definitions of Socialism, Planning, and the Welfare State, 1930–1950,” History of Political Economy (2025): https://doi.org/10.1215/00182702-11773500
- Aris Trantidis and Nick Cowen, “Hayek versus Trump,” Polity (2020): https://www.journals.uchicago.edu/doi/10.1086/707769
- André Azevedo Alves and John Meadowcroft, “Hayek’s Slippery Slope, the Stability of the Mixed Economy and the Dynamics of Rent Seeking,” Political Studies (2014): https://onlinelibrary.wiley.com/doi/full/10.1111/1467-9248.12043
Editorial limit: The publisher’s book description, chapter contents, publication history and academic research were checked. A full direct chapter-by-chapter comparison against a single specified edition remains to be completed before claiming close textual analysis.
Next step: test the next assumption
Full decision path →Continue with the decision framework, evidence, or review that changes the next action.
DISCUSSION
Questions, verification and corrections
Sign in to comment. Every new comment is reviewed before publication; while pending, it is visible only to you and the administrator.